
CFO特征对现金持有量影响及其区域市场化差别
2017-07-29 02:41:10李晓玲葛长付侯啸天
长安大学学报·社科版
2017年3期
李晓玲++葛长付++侯啸天
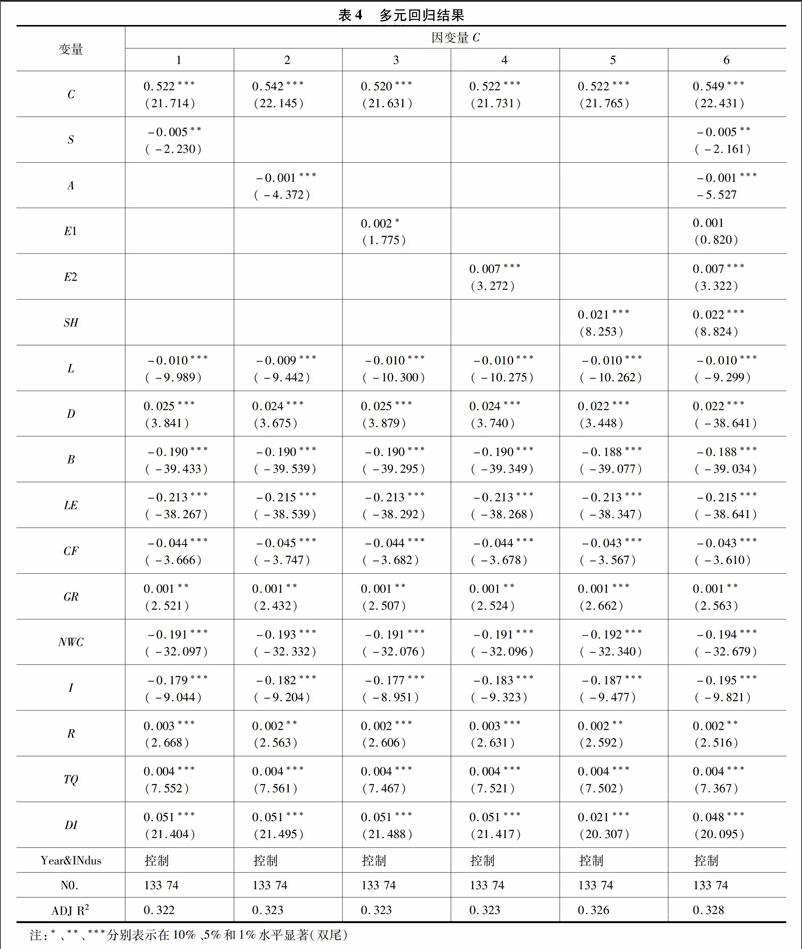
摘要:国内外学者基于权衡理论、融资优序理论和代理理论三大理论对现金持有量影响因素做了大量研究,而鲜有文献研究CFO特征对企业现金持有量的影响。以中国2006~2014年沪深两市A股上市公司数据为样本,实证研究了CFO特征对现金持有量的影响以及在不同区域市场化环境下的差异表现。研究表明:女性CFO所在的上市公司现金持有量低于男性CFO的上市公司;CFO年龄与上市公司现金持有量显著负相关,CFO的年龄越大,企业现金持有量越小;具有会计师、注册会计师、经济师等专业资格的CFO所在上市公司的现金持有量多于不具有这些专业资格的CFO所在上市公司;CFO股权激励与现金持有量显著正相关,但CFO学历对现金持有量没有显著影响;研究还发现,在不同市场化进程下,各地区CFO特征对现金持有量影响有明显差异。
关键词:CFO;现金持有量;区域市场化;股权激励;公司治理结构
中图分类号:F275
文献标志码:A文章编号:16716248(2017)03004512
[GK-2!-2]
The effect of CFO characteristics on cash holdings and the
difference in regional marketization
LI Xiaoling, GE Changfu, HOU Xiaotian
(School of Business,Anhui University,Hefei 230601, Anhui, China)
Abstract: Cash holdings Scholars home and abroad made a large number of research on the influencing factors of cash holdings based on tradeoff theory, pecking order theory, and agency cost theory. However, there is very few literature for the research of the impact of CFO characteristics on the cash holdings of enterprises. Taking Shanghai and Shenzhen Ashare listed companies data from 2006 to 2014 as sample, this paper did an empirical study on the effect of CFO characteristics on the cash holdings and the difference in regional marketization. The result shows that the listed companies with female CFO have lower cash holdings than that with male CFO. CFOs age is negatively correlated to the cash holdings of listed companies. The older the CFO gets, the smaller the cash holdings of listed companies becomes. The listed companies with the CFO who has more professional qualifications such as public accountants, CPA and economists have more cash holdings than that with the CFO who doesnt have. The correlation between stock option incentive and cash holdings is significantly positive, but there is no significant correlation between CFO education level and cash holdings. In addition, in the process of different marketization, the impact of CFO characteristics on cash holdings is obviously different in different regions.
Key words: CFO; cash holdings; regional marketization; stock option incentive; corporate governance structure
[GK-2!-2]
现金是企业的“血液”,是最为重要的流动资产,能够提高公司的财务柔性,降低财务风险。现金持有量是企业财务决策的核心内容,它关系到企业的正常生存和发展[12]。企业持有足够的现金可以减少外部融资需求,应对可能出现的风险。然而,持有较多现金会使企业出现投资不足,增加管理层利用现金谋私利的风险[3]。因此,研究现金持有问题具有重要的理论和现实意义。学者主要基于权衡理论、融资优序理论和代理理论三大理论,分别从公司治理结构[45]、财务特征[6]、投资者保护环境[7]、宏观经济政策[89]等方面研究了对现金持有水平的影响因素,取得了显著成果。……
登录APP查看全文
