投资性房地产会计政策选择因素分析
2021-07-14 17:46:56吴诗琪
中小企业管理与科技·上旬刊
2021年6期
吴诗琪
【摘 要】会计政策的选择是指在国家规定的会计政策范围内,企业可以根据自身发展情况,选择适合企业的会计政策。企业开展会计政策选择的原因包括2个方面:第一是方便企业核算和解决企业在经营中遇到的问题,第二是满足各利益相关群体的需求。上市公司选择不同的会计政策,既有利于形成与企业经营特色相关的会计核算系统,也有利于管理者更好地规划企业发展方向。
【Abstract】The accounting policy selection means that within the scope of accounting policy stipulated by the state, enterprises can select the accounting policy suitable for enterprises according to their own development condition. There are two reasons for enterprises to select accounting policy. The first is to facilitate enterprises to calculate and solve the problems encountered in the operation of enterprises. The second is to meet the needs of various stakeholders. The selection of different accounting policies of listed companies is not only beneficial to the formation of an accounting system related to the business characteristics of the enterprises, but also beneficial to the managers to better plan the development direction of the enterprises.
【關键词】投资性房地产;会计政策选择;公允价值计量模式;成本计量模式
【Keywords】investment real estate; accounting policy selection; fair value measurement mode; cost measurement mode
【中图分类号】F299.23 【文献标志码】A 【文章编号】1673-1069(2021)06-0164-02
1 研究背景
1978年,我国实行改革开放政策以后,我国的经济蓬勃发展。在经济全球化的带动下,我国的企业经营方式也日趋多元化和国际化,企业的日常经营范围逐渐扩大,经营产品逐渐复杂,企业相应的会计工作也逐渐多元化和复杂化。各行各业对于会计事项的需求逐渐出现差异化倾向。企业的不同利益相关者对获取的会计信息的重视程度也存在一定的差异性,会计信息使用者对企业信息质量的要求也越来越高。企业要良好发展就必须有高质量的企业信息以供判断和选择。在这样的大环境下,利益相关者和企业信息需求者对会计信息质量的要求在不断地提高,高质量的企业信息需要依赖正确的会计政策。
2 两种会计政策在我国的应用现状
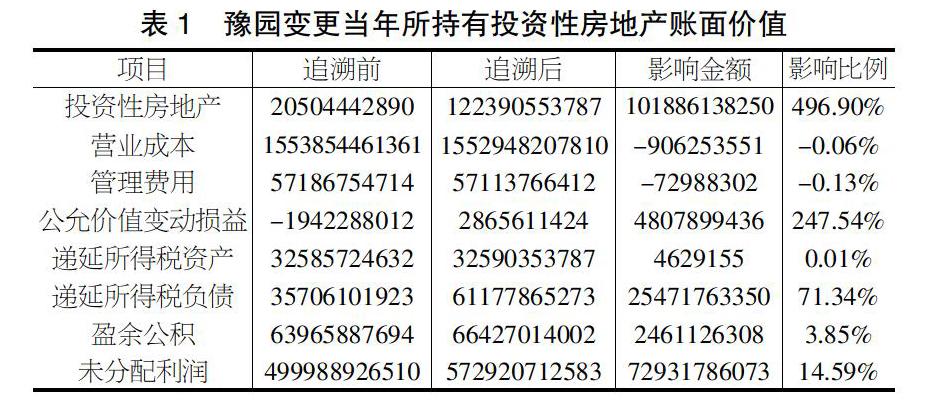
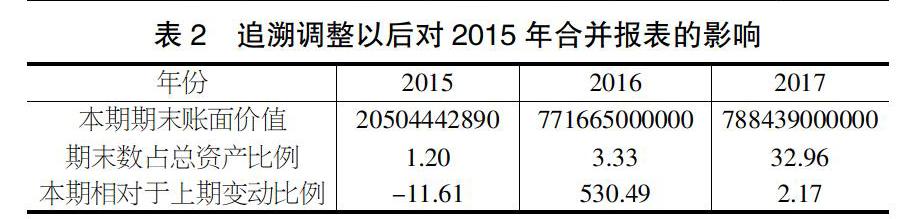
本文以上海豫园股份有限公司投资性房地产后续计量模式的会计政策选择为研究对象,主要分析两种不同的政策带来的不同结果。……
登录APP查看全文